Turbulent oil prices dropped to the low $30s on Thursday, falling to 16-year lows just hours after President Donald Trump announced a 30-day ban on travel from more than two dozen countries in Europe in an attempt to stem the spread of coronavirus.
Brent crude oil, the benchmark for global prices and for U.S. gasoline prices, had declined to nearly $33 a barrel as of midday Thursday, down from a one-day peak of $36 reached just an hour before Trump began his live remarks from the Oval Office.
West Texas Intermediate, the bellwether for U.S. shale oil production, saw a similarly dramatic drop, from $33.48 an hour before the president’s remarks Wednesday evening to close to $30 by the next afternoon.
Both Brent and WTI have seen their market values plunge by roughly a third from last week alone. Each is fetching less than half of what it was earning at the start of the year barely three months ago.
'The next 10-14 days are going to be pretty rough,' said Steven Kopits, managing director of Princeton Energy Advisors. 'There are going to be reversals here – big ones – almost on a daily basis: up 10-15 percent one day, then dropping again. So it's going to be really a rollercoaster ride without any real stability figure through at least next weekend.'
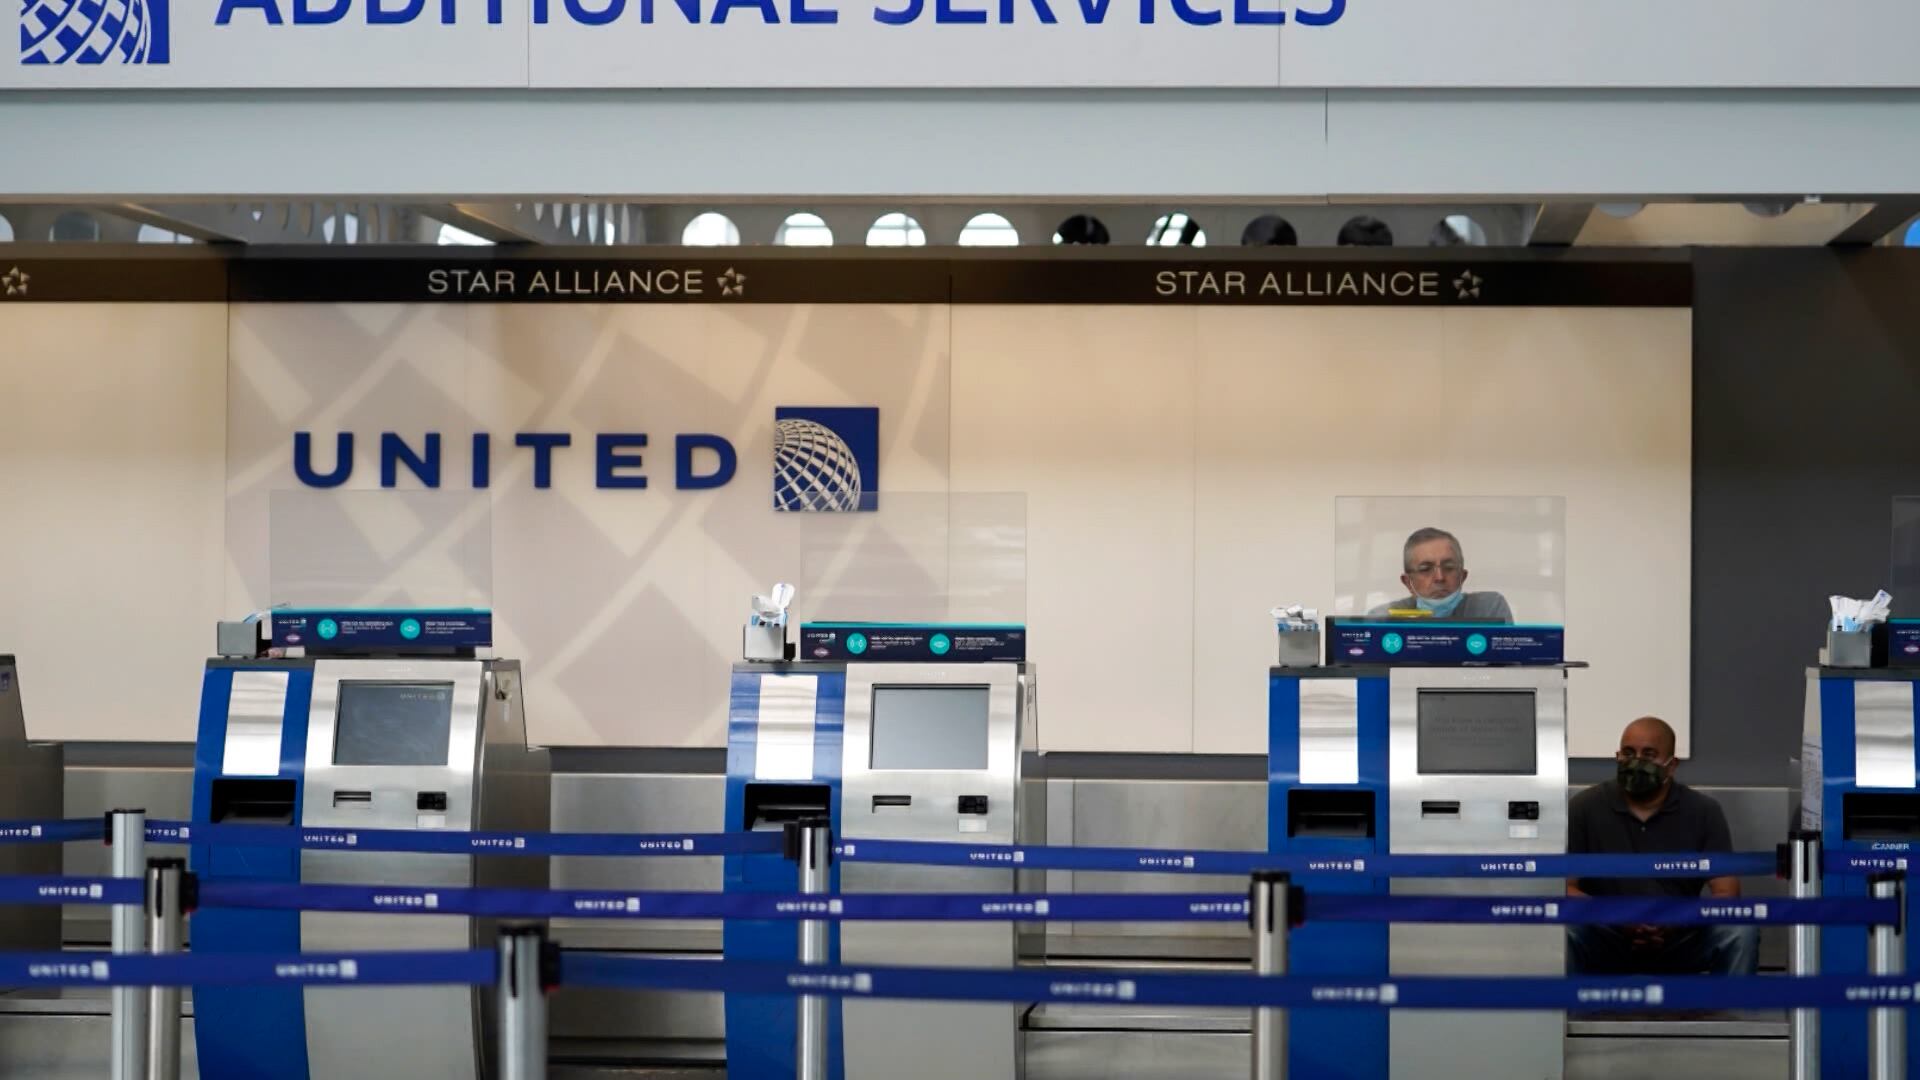
The plunging prices mirror similar slides in airline stocks: American Airlines and United Airlines have seen their market values decline by roughly 45 percent since the start of the year. Alaska Airlines’ stock price has tumbled by more than a third, while Delta, JetBlue, and Southwest have lost about a quarter of their respective market values.
Budget carrier Frontier Airlines on Thursday was offering up to 90 percent off on its domestic flights.
For both oil and airlines, the travel ban on Europe worsens the sudden drop-off of global demand sparked by the COVID-19 pandemic, which has spurred countries across the world to institute restrictions on travel, tourism, and shipping.
But greatly exacerbating the crisis, the oil sector, in particular, is also now drowning in an oversupply of crude, a deluge unleashed by the eruption of a price war between Saudi Arabia and Russia.
The two countries, the world’s No. 2 and No. 3 oil producers behind the U.S., failed last weekend to renew an agreement on production cuts that had helped shore-up flagging prices. In response, Saudi Crown Prince Mohammed bin Salman announced a surprise price cut and a sudden increase in production in a move widely seen as an attempt to both grab market share and punish Moscow by torpedoing the oil prices that both Saudi Arabia and Russia depend on for revenue.
Oil prices quickly began to nosedive. The pain is particularly pronounced among U.S. oil and gas producers, who rely on techniques such as hydraulic fracturing – or fracking – and horizontal drilling to extract fossil fuels from porous shale rock formations deep underground, which are more expensive than conventional drilling.
The biggest players in the U.S. shale oil industry, such as Occidental Petroleum and Continental Resources, have seen their market values drop by as much as 50 percent. Job losses in the sector are expected to reach tens of thousands. If benchmark oil prices fall to $26-28, not seen since February 2016 after Saudi Arabia last ramped-up production to grab market share, producers may be forced to shut-in their wells and stop extraction altogether.
'We're pretty close to that here,' Kopits said. 'If the Saudis persist in this policy for an extended period of time, we will be seeing out-and-out bankruptcies in the shale sector in significant numbers. Things are really dire if you have to shut-in your production.'
Without an agreement between Russia and Saudi-led OPEC – a partnership often referred to as OPEC-plus – consulting firm Rystad Energy warned Wednesday that prices could fall even further into the low-$20s.
'The global oil market has lost its regulator and now only market mechanisms can dictate the balance between supply and demand,' Espen Erlingsen, Rystad’s head of upstream research, said in a statement.
Nonetheless, Airlines 4 America, the main trade group for U.S. airlines, praised the administration’s moves in a statement Wednesday evening.
'We commend President Trump for continuing to take decisive action to protect the health and well-being of the American people. For U.S. airlines, the safety of our passengers, crew and cargo is – and always will be – our top priority,' A4A President and CEO Nicholas Calio said. 'The unforeseen outbreak of the coronavirus has directly impacted the U.S. airline industry, which is critical to the U.S. and global economies. This action will hit U.S. airlines, their employees, travelers and the shipping public extremely hard. However, we respect the need to take this unprecedented action and appreciate the Administration’s commitment to facilitate travel and trade.'